The market for logistics and manufacturing real estate has stabilized once again. With a take-up of approximately 216,000 square meters in 2025, the weak result from 2024 was significantly surpassed. In the first half of 2026, approximately 115,500 square meters were already transacted, suggesting that space turnover for the full year will once again reach the previous year’s level. As of the first half of the year, approximately 109,500 square meters were attributable to leases and only about 6,000 square meters to owner-occupancy.
This indicates that the market continues to stabilize despite the ongoing challenging macroeconomic conditions. Challenges in the manufacturing sector continue to dampen demand. At the same time, the need for modern logistics and production space available at short notice remains fundamentally strong.
As a result, the prime rent for logistics and warehouse space will remain unchanged at 6.40 euros/sqm in 2026. The average rent is reported at 4.90 euros/sqm, slightly below the previous year’s figure of 5.00 euros/sqm. For retail space, the prime rent rises slightly from 7.30 to 7.40 euros/sqm, while the average rent remains stable at 6.20 euros/sqm.
Supply and Project Pipeline
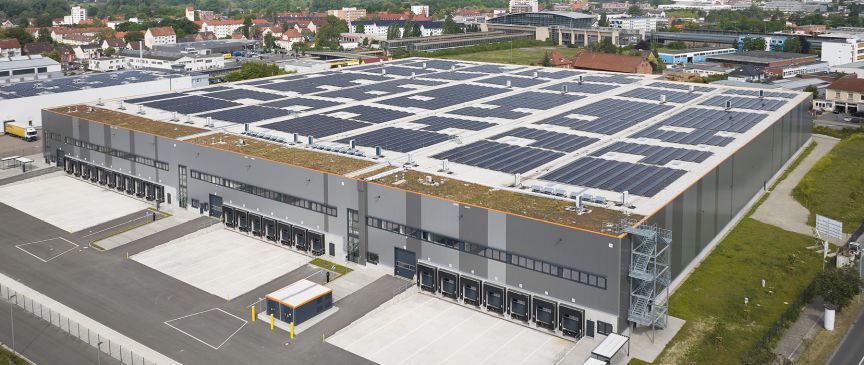
On the supply side, too, the market remains dynamic. For 2026, completions and projects in the pipeline total approximately 100,000 square meters of warehouse and commercial space. These projects include, among others, the Panattoni Park Hannover Zentrum, as well as other projects in Hannover, Garbsen, and the surrounding area. For 2027 and 2028, an additional approximately 200,000 square meters are currently in the pipeline, including the logistics center currently under construction in Barsinghausen. The project pipeline thus remains well-stocked despite the challenging market environment. At the same time, new developments are being implemented much more selectively than during the boom years.
In total, the recorded logistics real estate portfolio in the Hanover region currently comprises approximately 4.17 million square meters across 372 properties. Despite the challenging economic environment, the current project developments thus continue to underscore the importance of the Hanover region as a logistics and manufacturing hub.
Market Outlook: New Demand Drivers Meet Economic Uncertainty
In the first half of 2026, the German logistics real estate market showed initial signs of a recovery. At the same time, the market environment remains challenging. In addition to the continued weak economic performance, geopolitical uncertainties are creating additional headwinds. In particular, the rise in energy costs resulting from the Iran conflict is increasing cost pressures on industry and logistics and may delay investment and location decisions.
Despite short-term uncertainties, new drivers of demand are emerging that could trigger additional space requirements for logistics, production, and light industrial use in the medium to long term:
- Defense and defense-related industries: The significant increase in defense spending is leading to capacity expansions among companies in the defense industry and their suppliers. The resulting demand for space has so far been particularly evident in production space and owner-occupier solutions, rather than in the form of a broad increase in traditional logistics leasing. Looking ahead, however, logistics service providers, suppliers, and specialized project developments may also benefit from additional space requirements. The Hanover region offers fundamentally good location conditions for this purpose due to its central location, industrial base, and efficient transportation infrastructure.
- Growing demand from Asian e-commerce providers: Chinese and other Asian online retailers, as well as their affiliated logistics service providers, are continuing to expand their presence in the German market. This is increasing the need for large-scale distribution centers from which the German and European markets can be served. The Hanover region can benefit from its central location within Germany and its connections to key north-south and east-west transportation corridors.
In the medium to long term, conditions therefore remain favorable for rising demand for warehouse space. In particular, the region’s central location and efficient logistics infrastructure—including the A2 and A7 highways, rail freight transport, and proximity to northern German seaports—strengthen its position as a supraregional distribution hub. In addition to traditional logistics and manufacturing companies, courier, express, and parcel services, as well as new user groups, can benefit from this.
In the short term, however, the continued weak economic performance in Germany is overshadowing these structural growth drivers. It is particularly affecting concrete demand for space from the manufacturing sector and continues to lead to, in some cases, longer decision-making processes for leases and project developments.
The Hanover region maintains its position as a strong and resilient logistics hub
Over many years, the Hanover region has established itself as a major hub for logistics and industry. Its central location within Germany and its efficient transportation infrastructure constitute a key locational advantage. At the same time, the approach to available commercial space is changing. In addition to more conservative and targeted rezoning, the focus is shifting increasingly toward the activation of previously used sites.
Contact
Dr. Kai Ingwersen
Hanover Region
Economic Development
Department of Economic and Employment Development